ASC 606
The Usage-Based Revenue Recognition Playbook
6
Judgment calls, each with a decision tree and journal entries
ASC 606
Every conclusion cited to the subparagraph, not the section
2
Big-4 handbooks cross-checked for every position
The Six Questions
The judgment calls that stall an AI-native close
The Six Questions
Each links straight into the full analysis: theory, a realistic scenario, a decision tree, and the operational fix.
Fine-Tuning, Custom Models & Setup Fees
Outcome-Based & Agentic Pricing
Principal vs. Agent: Gross vs. Net
Prepaid Credits & Breakage
Period-End Unbilled Usage & Cutoff
Costs to Obtain a Contract
What's Inside
Every question, worked four ways
What's Inside
This isn’t a summary of the standard. Each question is worked end-to-end in the same four-part structure, so you move from “what does the codification say” to “what do I book Monday” without leaving the page.
Accounting Theory
Business Scenario
Decision Tree
Operational Solution
Where to Focus
Not every question is equally common, or equally costly
Where to Focus
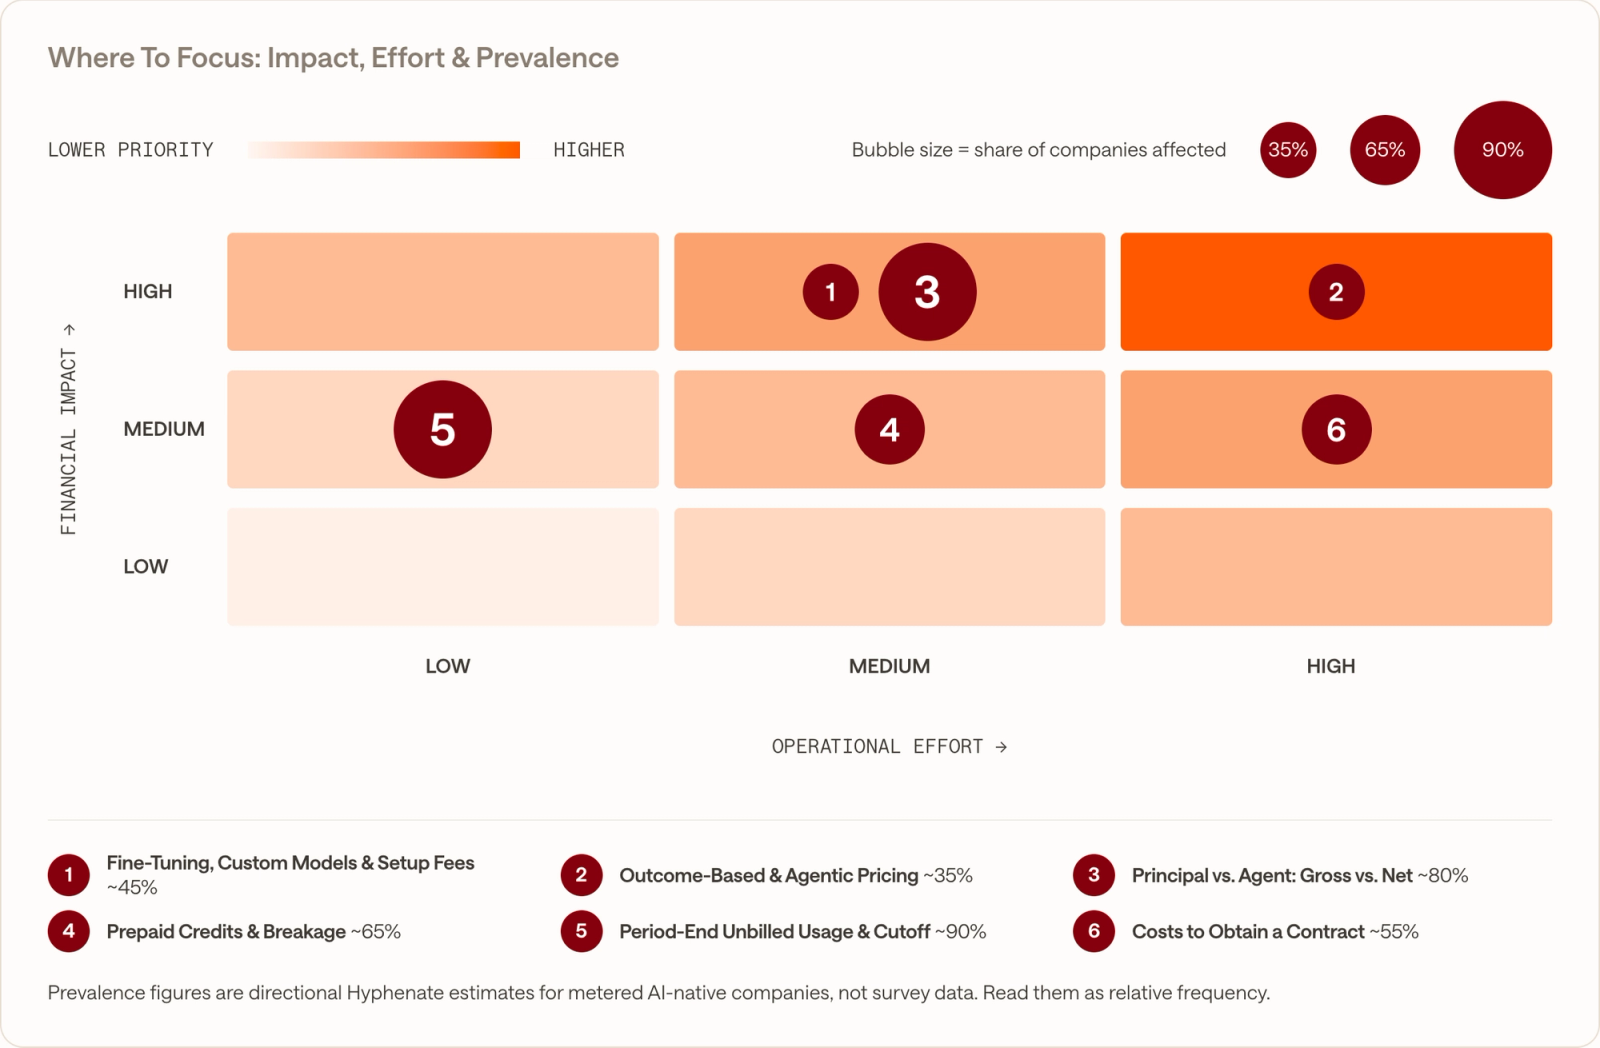
Each question plotted on financial impact and operational effort; bubble size shows roughly how many metered, AI-native companies actually run into it. Cutoff and gross-versus-net touch nearly everyone; outcome-based pricing is far rarer today but carries the highest financial stakes.
Sources & Precision
Cited to the subparagraph, not the section
Sources & Precision
Every reference points to the specific subparagraph that carries the conclusion, cross-checked against two Big-4 handbooks. Where a call is fact-dependent, the guide says so rather than overstate certainty.
ASC 606
ASC 340-40
Big-4 Handbooks
The Playbook
Take the full guide with you
The Playbook
The complete playbook: every question with codification references, journal entries, decision trees, and the operational fix.
- All six questions, fully worked
- Illustrative journal entries and true-ups
- Cross-checked gainst 2 Big-4 handbooks
Download the PDF
Subscribe to our newsletter to receive the latest from Hyphenate.